

Springer
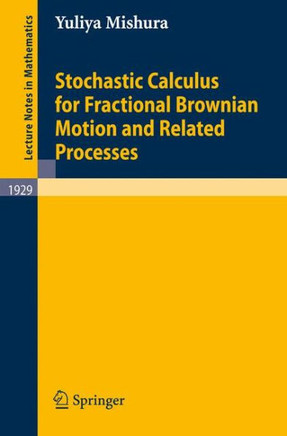
Stochastic Calculus for Fractional Brownian Motion and Related Processes
Product Code:
9783540758723
ISBN13:
9783540758723
Condition:
New
$87.33
Stochastic Calculus for Fractional Brownian Motion and Related Processes
$87.33
This volume examines the theory of fractional Brownian motion and other long-memory processes. Interesting topics for PhD students and specialists in probability theory, stochastic analysis and financial mathematics demonstrate the modern level of this field. It proves that the market with stock guided by the mixed model is arbitrage-free without any restriction on the dependence of the components and deduces different forms of the Black-Scholes equation for fractional market.
| Author: Yuliya Mishura |
| Publisher: Springer |
| Publication Date: Nov 30, 2007 |
| Number of Pages: 398 pages |
| Binding: Paperback or Softback |
| ISBN-10: 3540758720 |
| ISBN-13: 9783540758723 |
Related Products